
9:41


Account details
Beneficiary
Michael Thompson


Account number
2387 •••• 9021
Routing number
0210 •••• 21
SWIFT code
XXXXUS33
Bank name and address
[Partner bank], N.A.
New York, NY
Share details


Transfers to these details arrive in your [YourBrand] USD balance.

[Your Brand]

CUSTOMER NAME
06/28
1234 1234 1234 1234


Account opened
In your customer’s name


Payment received
Arrives as [Your App] USD


Sent to CLABE
MXN 50,000.00


For fintechs and remittance
Dollar accounts, transfers and a card.
Under your brand.
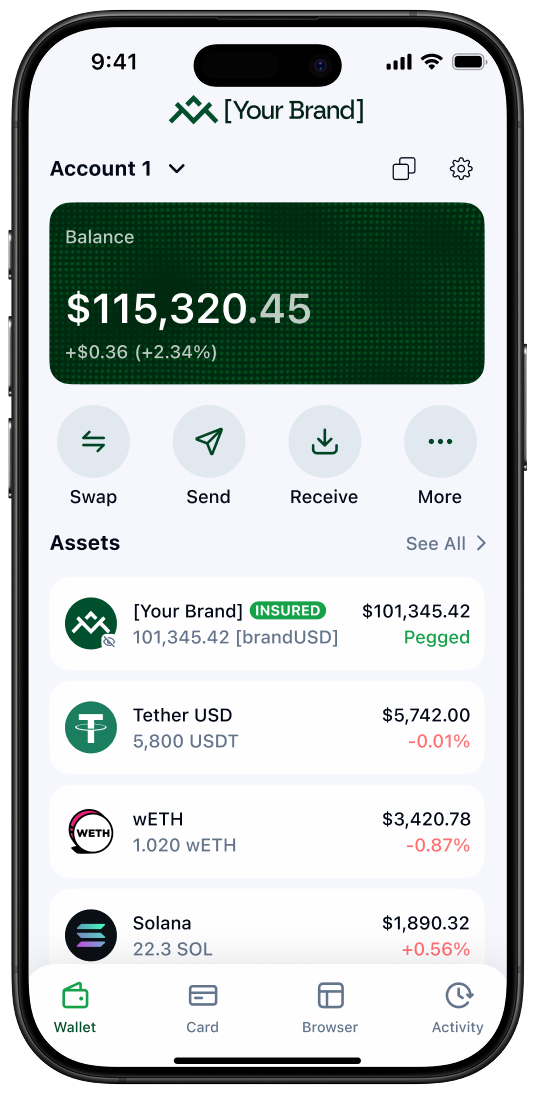
Launch a branded money app with named accounts in USD, EUR, MXN and others, transfers to bank accounts, and a card. Licensed partners provide the accounts and cards; you keep the customer.

Your customers want dollar accounts anda card.
Building a bank to offer them would take years.


A banking stack takes years
Building or licensing one needs years of work and a large budget.


Cross-border is slow and costly
Customers pay high fees and wait days to move money home.


Balances earn nothing for you
Customer money sits with partners and earns for someone else.
Fintechs usually call us when

Customers ask for dollar accounts or a card
A rival launches one
Your banking partner raises fees or drops fintech clients
You launch in a new country
Everything your customers ask for, under your brand
Accounts, transfers and a card first. More products when you’re ready.


Payment received
Arrives as [Your App] USD


Account opened
In your customer’s name
Named accounts in your customers’ names
Open accounts in USD, EUR, MXN and others through licensed partners, subject to eligibility and availability. Customers get paid by bank transfer, and payments arrive as your branded balance.

Account details customers can share
Payments in from local bank rails
Every account under your brand

[Your Brand]

CUSTOMER NAME
06/28
1234 1234 1234 1234


Sent to CLABE
MXN 50,000.00


Interchange earned
On every card payment
Send to any bank account.
Spend anywhere.
Customers send to IBAN, CLABE and ACH accounts with competitive FX fees, day or night, with rates and fees shown before every transfer. Your branded card spends the same balance anywhere cards are accepted, and you earn interchange on every payment.
IBAN, CLABE and ACH
Competitive FX fees
Virtual and physical cards
Interchange on every payment
Add more whenyou’re ready
Grow into a full branded money app on mass[Finance], our platform for branded money apps, built on the same stack.


Credit
Credit secured by your customers’ balance, or credit provided by you. Subject to eligibility and approval.
Product preview


Tokenized money market funds
Investments, not deposits. Capital at risk; returns are not guaranteed. Available to eligible users where permitted.
Product preview


Your own branded currency
Created automatically with your app. It converts one for one to and from major stablecoins through VDCC.
Product preview
What could your customers’ balancesearn you?
Revenue comes from the reserve behind branded balances, plus card interchange and FX spreads.
Illustrative estimate, not a forecast. Actual revenue depends on balances, market rates and fees, and is not guaranteed.


Launch cost, compared
Tens of millions
To build from scratch: regulatory, technology and distribution
$3K–$100K a year
To launch on mass[Finance]
Source: mass[Finance] estimates, Nov 2026. Illustrative.
See a branded money app in action
Built for remittance and fintech teams. Send them to your product and finance leads.
Up next

mass[Finance]


Coming soon
Launch a
money app
How to · Launch


Launch a branded money app
How to · Coming soon
mass[Finance]
Coming soon
Pay any
bank account
How to · Bank transfers
Send money to abank account:
IBAN, CLABE, ACH
How to · Coming soon
mass[Finance]
Coming soon
What your
app earns
Explained · Revenue
The math: what a branded moneyapp earns
Explained · Coming soon
mass[Wallets]
Coming soon
Get and use
the card
How to · Cards
How your users get and use a card
How to · Coming soon
Questions fintechs ask us
We don’t have a banking license.
You don’t need your own. The app runs on stablecoin infrastructure, and licensed partners provide accounts and cards, subject to eligibility and availability.
Where does the money sit?
Customers hold their balance in their own non-custodial wallet, as your branded balance. Fiat accounts sit with licensed partners. Branded balances are not bank deposits.
Do we need a separate project for our own currency?
No. Your app gets its own branded currency automatically. It converts one for one to and from major stablecoins through VDCC, for a flat fee.
Which countries can we launch in?
The wallet works across markets. Accounts, cards and ramps depend on partner coverage in each country, so we map your markets on the first call.
See a demo
with your logo
Your wallet, card and named accounts in your brand, as a two-minute video or a live demo.
Request your branded demo

Vaulton runs its own branded app for high-net-worth clients on the same platform.
Important information
• Illustrative estimate, not a forecast. Actual revenue depends on balances, market rates and fees, and is not guaranteed.
• Credit, tokenized money market funds and branded currencies are in product preview, subject to counsel in each market.
• mass[Wallets] is a technology platform from Decentralized Clearing Inc., not a bank. Accounts, cards, payments and on/off-ramp services are provided by licensed third-party partners, subject to eligibility and availability. Branded balances are not bank deposits and are not FDIC insured. Digital assets involve risk. Not investment advice. Screens and figures are illustrative.

© 2026 mass[Wallets]. All rights reserved.

All content provided here is for informational purposes only. Nothing on this site constitutes a solicitation, an offer to sell securities, or any form of legal, tax, or financial advice. Anyone considering involvement in the mass[Currency] ecosystem should seek independent professional guidance on legal, tax, or financial matters. No token referenced in this document has been registered or qualified under any U.S. federal, state, or foreign securities laws or regulations.
By accessing or using this website, you confirm your understanding and acceptance of this disclaimer and the applicable Terms and Conditions. You alone are responsible for assessing the risks and benefits of any actions you take based on the content herein.
9:41


Account details
Beneficiary
Michael Thompson


Account number
2387 •••• 9021
Routing number
0210 •••• 21
SWIFT code
XXXXUS33
Bank name and address
[Partner bank], N.A.
New York, NY
Share details


Transfers to these details arrive in your [YourBrand] USD balance.

[Your Brand]

CUSTOMER NAME
06/28
1234 1234 1234 1234


Account opened
In your customer’s name


Payment received
Arrives as [Your App] USD


Sent to CLABE
MXN 50,000.00
For fintechs and remittance
Dollar accounts, transfersand a card.
Under your brand.
Launch a branded money app with named accounts in USD, EUR, MXN and others, transfers to bank accounts, and a card. Licensed partners provide the accounts and cards; you keep the customer.
Your customers want dollar accounts anda card.
Building a bank to offer them wouldtake years.
A banking stack takes years
Building or licensing one needs years of work and a large budget.
Cross-border is slow and costly
Customers pay high fees and wait days to move money home.
Balances earn nothing for you
Customer money sits with partners and earns for someone else.
Fintechs usually call us when
Customers ask for dollar accounts or a card
A rival launches one
Your banking partner raises fees or drops fintech clients
You launch in a new country
Everything your customers ask for, under your brand
Accounts, transfers and a card first. More products when you’re ready.


Payment received
Arrives as [Your App] USD


Account opened
In your customer’s name
Named accounts in your customers’ names
Open accounts in USD, EUR, MXN and others through licensed partners, subject to eligibility and availability. Customers get paid by bank transfer, and payments arrive as your branded balance.
Account details customers can share
Payments in from local bank rails
Every account under your brand


[Your Brand]

CUSTOMER NAME
06/28
1234 1234 1234 1234


Sent to CLABE
MXN 50,000.00


Interchange earned
On every card payment
Send to any bank account.
Spend anywhere.
Customers send to IBAN, CLABE and ACH accounts with competitive FX fees, day or night, with rates and fees shown before every transfer. Your branded card spends the same balance anywhere cards are accepted, and you earn interchange on every payment.
IBAN, CLABE and ACH
Competitive FX fees
Virtual and physical cards
Interchange on every payment
Add more when you’re ready
Grow into a full branded money app on mass[Finance], our platform for branded money apps, built on the same stack.
Credit
Credit secured by your customers’ balance, or credit provided by you. Subject to eligibility and approval.
Product preview
Tokenized money market funds
Investments, not deposits. Capital at risk; returns are not guaranteed. Available to eligible users where permitted.
Product preview
Your own branded currency
Created automatically with your app. It converts one for one to and from major stablecoins through VDCC.
Product preview
What could your customers’ balancesearn you?
Revenue comes from the reserve behind branded balances, plus card interchange and FX spreads.
Illustrative estimate, not a forecast. Actual revenue depends on balances, market rates and fees, and is not guaranteed.
Launch cost, compared
Tens of millions
To build from scratch: regulatory, technology and distribution
$3K–$100K a year
To launch on mass[Finance]
Source: mass[Finance] estimates, Nov 2026. Illustrative.
See a branded money app in action
Built for remittance and fintech teams. Send them to your product and finance leads.
Up next
mass[Finance]
Coming soon
Launch a
money app
How to · Launch
Launch a branded money app
How to · Coming soon
mass[Finance]
Coming soon
Pay any
bank account
How to · Bank transfers
Send money to a bank account:
IBAN, CLABE, ACH
How to · Coming soon
mass[Finance]
Coming soon
What your
app earns
Explained · Revenue
The math: what a branded money app earns
Explained · Coming soon
mass[Wallets]
Coming soon
Get and use
the card
How to · Cards
How your users get and use a card
How to · Coming soon
Questions fintechs ask us
We don’t have a banking license.
You don’t need your own. The app runs on stablecoin infrastructure, and licensed partners provide accounts and cards, subject to eligibility and availability.
Where does the money sit?
Customers hold their balance in their own non-custodial wallet, as your branded balance. Fiat accounts sit with licensed partners. Branded balances are not bank deposits.
Do we need a separate project for our own currency?
No. Your app gets its own branded currency automatically. It converts one for one to and from major stablecoins through VDCC, for a flat fee.
Which countries can we launch in?
The wallet works across markets. Accounts, cards and ramps depend on partner coverage in each country, so we map your markets on the first call.
See a demo
with your logo
Your wallet, card and named accounts in your brand, as a two-minute video or a live demo.
Request your branded demo
Vaulton runs its own branded app for high-net-worth clients on the same platform.
Important information
• Illustrative estimate, not a forecast. Actual revenue depends on balances, market rates and fees, and is not guaranteed.
• Credit, tokenized money market funds and branded currencies are in product preview, subject to counsel in each market.
• mass[Wallets] is a technology platform from Decentralized Clearing Inc., not a bank. Accounts, cards, payments and on/off-ramp services are provided by licensed third-party partners, subject to eligibility and availability. Branded balances are not bank deposits and are not FDIC insured. Digital assets involve risk. Not investment advice. Screens and figures are illustrative.


© 2026 mass[Wallets]. All rights reserved.

All content provided here is for informational purposes only. Nothing on this site constitutes a solicitation, an offer to sell securities, or any form of legal, tax, or financial advice. Anyone considering involvement in the mass[Currency] ecosystem should seek independent professional guidance on legal, tax, or financial matters. No token referenced in this document has been registered or qualified under any U.S. federal, state, or foreign securities laws or regulations.
By accessing or using this website, you confirm your understanding and acceptance of this disclaimer and the applicable Terms and Conditions. You alone are responsible for assessing the risks and benefits of any actions you take based on the content herein.
For fintechs and remittance
Dollar accounts, transfers
and a card.
Under your brand.
Launch a branded money app with named accounts in USD, EUR, MXN and others, transfers to bank accounts, and a card. Licensed partners provide the accounts and cards; you keep the customer.
9:41
Account details
Beneficiary
Michael Thompson
Account number
2387 •••• 9021
Routing number
0210 •••• 21
SWIFT code
XXXXUS33
Bank name and address
[Partner bank], N.A.
New York, NY
Share details
Transfers to these details arrive in your [YourBrand] USD balance.
[Your Brand]
CUSTOMER NAME
06/28
1234 1234 1234 1234

Account opened
In your customer’s name

Payment received
Arrives as [Your App] USD

Sent to CLABE
MXN 50,000.00
Your customers want dollar accounts and a card.
Building a bank to offer them would take years.
A banking stack takes years
Building or licensing one needs years of work and a large budget.
Cross-border is slow and costly
Customers pay high fees and wait days to move money home.
Balances earn nothing for you
Customer money sits with partners and earns for someone else.
Fintechs usually call us when
Customers ask for dollar accounts or a card
A rival launches one
Your banking partner raises fees or drops fintech clients
You launch in a new country
Everything your customers ask for, under your brand
Accounts, transfers and a card first. More products when you’re ready.
Named accounts in your
customers’ names
Open accounts in USD, EUR, MXN and others through licensed partners, subject to eligibility and availability. Customers get paid by bank transfer, and payments arrive as your branded balance.

Account details customers can share
Payments in from local bank rails
Every account under your brand

Payment received
Arrives as [Your App] USD

Account opened
In your customer’s name
[Your Brand]
CUSTOMER NAME
06/28
1234 1234 1234 1234

Sent to CLABE
MXN 50,000.00

Interchange earned
On every card payment
Send to any bank account.
Spend anywhere.
Customers send to IBAN, CLABE and ACH accounts with competitive FX fees, day or night, with rates and fees shown before every transfer. Your branded card spends the same balance anywhere cards are accepted, and you earn interchange on every payment.
IBAN, CLABE and ACH
Competitive FX fees
Virtual and physical cards
Interchange on every payment
Add more when you’re ready
Grow into a full branded money app on mass[Finance], our platform for branded money apps, built on the same stack.
Credit
Credit secured by your customers’ balance, or credit provided by you. Subject to eligibility and approval.
Product preview
Tokenized money market funds
Investments, not deposits. Capital at risk; returns are not guaranteed. Available to eligible users where permitted.
Product preview
Your own branded currency
Created automatically with your app. It converts one for one to and from major stablecoins through VDCC.
Product preview
What could your customers’ balances earn you?
Revenue comes from the reserve behind branded balances, plus card interchange and FX spreads.
Illustrative estimate, not a forecast. Actual revenue depends on balances, market rates and fees, and is not guaranteed.
Launch cost, compared
Tens of millions
To build from scratch: regulatory, technology and distribution
$3K–$100K a year
To launch on mass[Finance]
Source: mass[Finance] estimates, Nov 2026. Illustrative.
See a branded money app in action
Built for remittance and fintech teams. Send them to your product and finance leads.
Up next
mass[Finance]
Coming soon
Launch a
money app
How to · Launch
Launch a branded money app
How to · Coming soon
mass[Finance]
Coming soon
Pay any
bank account
How to · Bank transfers
Send money to a bank account:
IBAN, CLABE, ACH
How to · Coming soon
mass[Finance]
Coming soon
What your
app earns
Explained · Revenue
The math: what a
branded money app earns
Explained · Coming soon
mass[Wallets]
Coming soon
Get and use
the card
How to · Cards
How your users get
and use a card
How to · Coming soon
Questions fintechs ask us
We don’t have a banking license.
You don’t need your own. The app runs on stablecoin infrastructure, and licensed partners provide accounts and cards, subject to eligibility and availability.
Where does the money sit?
Customers hold their balance in their own non-custodial wallet, as your branded balance. Fiat accounts sit with licensed partners. Branded balances are not bank deposits.
Do we need a separate project for our own currency?
No. Your app gets its own branded currency automatically. It converts one for one to and from major stablecoins through VDCC, for a flat fee.
Which countries can we launch in?
The wallet works across markets. Accounts, cards and ramps depend on partner coverage in each country, so we map your markets on the first call.
See a demo
with your logo
Your wallet, card and named accounts in your brand, as a two-minute video or a live demo.
Request your branded demo
Vaulton runs its own branded app for high-net-worth clients on the same platform.
Important information
• Illustrative estimate, not a forecast. Actual revenue depends on balances, market rates and fees, and is not guaranteed.
• Credit, tokenized money market funds and branded currencies are in product preview, subject to counsel in each market.
• mass[Wallets] is a technology platform from Decentralized Clearing Inc., not a bank. Accounts, cards, payments and on/off-ramp services are provided by licensed third-party partners, subject to eligibility and availability. Branded balances are not bank deposits and are not FDIC insured. Digital assets involve risk. Not investment advice. Screens and figures are illustrative.

© 2026 mass[Wallets]. All rights reserved.

All content provided here is for informational purposes only. Nothing on this site constitutes a solicitation, an offer to sell securities, or any form of legal, tax, or financial advice. Anyone considering involvement in the mass[Currency] ecosystem should seek independent professional guidance on legal, tax, or financial matters. No token referenced in this document has been registered or qualified under any U.S. federal, state, or foreign securities laws or regulations.
By accessing or using this website, you confirm your understanding and acceptance of this disclaimer and the applicable Terms and Conditions. You alone are responsible for assessing the risks and benefits of any actions you take based on the content herein.